To understand which savings account will earn you the least money, you need to pay close attention to the Annual Percentage Yield (APY.) The APY is a crucial factor that indicates how much interest your money will earn over a year, considering compound interest.
Essentially, a lower APY, such as those offered by traditional banks, means your money grows at a snail’s pace. In contrast, higher APYs found in online-only and high-yield savings accounts ensure that your savings grow more substantially.
So, aim for an APY higher than 0.46%. Accounts with lower rates are less beneficial for growing your money. For example, a savings account with an APY of 0.01% will do very little to increase your balance, especially after considering inflation.
On the other hand, accounts with APYs above 1.00% can help your savings keep pace with or even outgrow inflation, preserving your purchasing power over time.
Typical Brick-and-Mortar Bank Accounts Will Earn You the Least Money
If you are wondering which savings account will earn you the least money, traditional brick-and-mortar banks like The Bank of America and Chase are prime examples. The Bank of America offers a meager 0.01% Annual Percentage Yield (APY), which is almost negligible. This means that if you had $10,000 in your savings account, you would earn just $1 in interest over an entire year.
Similarly, Chase is not much better, with an APY of 0.05%. These rates are a no-no if you are serious about growing your savings.
Sure! The convenience of having a physical branch might be appealing. But the return on your money certainly is not.
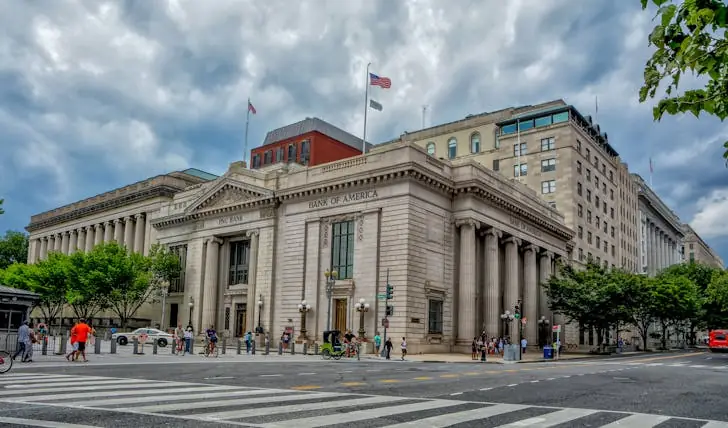
Brick-and-mortar banks typically have higher overhead costs. Hence, their interest rates on savings accounts are so low. They need to maintain physical locations, pay staff, and cover other expenses that online-only banks do not have.
Online-Only Savings Accounts Will Earn You More Money!
In stark contrast to traditional banks, online-only savings accounts offer much better returns. These banks do not have the overhead costs associated with maintaining physical branches, allowing them to pass the savings on to you in the form of higher interest rates. For example, banks like Ally and Discover offer APYs upwards of 0.90% to 1.00%.
With these rates, a $10,000 deposit could earn you around $100 in interest per year, which is a significant improvement over brick-and-mortar banks. So, if you are looking to grow your savings without the need for a physical branch, online-only savings accounts are a solid choice.
High-yield Savings Accounts are the Top Money-earners
When considering which savings account will earn you the least money, it is also essential to look at the other end of the spectrum: High-yield savings accounts. These accounts offer some of the highest APYs available, often exceeding 1.00%.
For example, Marcus by Goldman Sachs and American Express National Bank offer APYs around 1.20% to 1.25%. With a $10,000 deposit, you could earn approximately $120 to $125 in interest annually, which significantly boosts your savings potential.
High-yield savings accounts are ideal for those who want their money to work harder without risking it in investments. These accounts are typically offered by both online-only banks and some traditional banks looking to compete with online rates. They often come with no minimum balance requirements and low fees. Thus, this makes them accessible to a wide range of savers.
So, if maximizing your interest earnings is your goal, high-yield savings accounts are the way to go.